
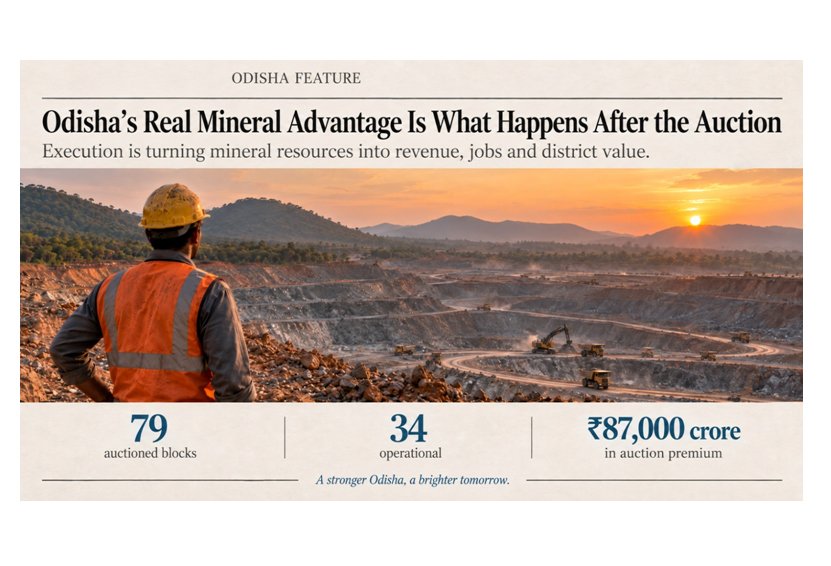
With 34 of 79 auctioned blocks already operational and 45 more in the pipeline, Odisha shows how execution can turn mineral resources into revenue, jobs and district value
In Odisha, the mineral economy is not an abstract national statistic. It is part of the State’s industrial landscape and the future of mineral-bearing districts. The important question is no longer whether Odisha has resources. It is how effectively those resources move from auction to operation, and how steadily the resulting value reaches the State, industry and local communities.
Thirty-four operating blocks change the conversation
Since mineral auctions began in 2015, Odisha has auctioned 79 blocks and brought 34 into operation, the highest operational tally among the States. Around ₹87,000 crore in auction premium accrued to Odisha between FY 2020-21 and FY 2025-26. Another 45 blocks are already in the pipeline. The State has around 600 mining leases across nearly 1,00,000 hectares, with approximately 130 to 140 mines working at any given time.
The number 34 matters because it represents conversion. An auction establishes the opportunity; an operating mine begins the recurring cycle of production, jobs, royalty, premium and supply to downstream industry. For Odisha, the next 45 blocks represent the scale of what can come next if that conversion continues.
Odisha’s story is part of a stronger State-led mineral economy
Across India, annual State mineral revenue rose from ₹25,206 crore in 2014-15 to ₹1,14,549 crore in 2025-26, a 354 per cent increase. Over the twelve-year period, ₹7,67,548 crore accrued to the States. Their share of mineral revenue rose from 60.24 per cent to 88.53 per cent, or close to 90 per cent.
Major mining States received more than ₹5 lakh crore between FY 2015-16 and FY 2025-26, while the Centre received around ₹82,000 crore. Royalty, auction premium, DMF, NMET and the State share of GST continue under the amended framework. Nearly 50 minor minerals remain within the existing State framework. For Odisha, where auctioned assets have been brought into production at scale, this continuity has direct fiscal significance.
In mineral districts, the value must be visible above the ground
Across India, 656 District Mineral Foundations, including 106 in aspirational districts, channel royalty-linked resources towards roads, healthcare, schools and drinking water. Jharkhand offers a companion example with around ₹19,000 crore collected through DMFs across all 24 districts.
For Odisha’s mineral-bearing districts, including places such as Keonjhar and Sundargarh, this is the human side of the mineral economy. A productive mine is not only a source of ore. It can also sustain livelihoods and strengthen the local resource base available for public priorities. Nationally, non-coal mining supports more than one crore direct and indirect jobs, while coal supports more than 25 lakh.
The Indian market gives Odisha a second growth story
India imported minerals worth ₹10,12,529 crore in FY 2025-26. Industrial minerals accounted for ₹1,18,330 crore. The import basket includes materials closely connected with Odisha’s strengths: iron ore worth ₹11,115 crore, manganese ₹10,872 crore, bauxite ₹4,822 crore and chromite ₹753 crore. Copper ores accounted for ₹52,670 crore, phosphorite ₹16,410 crore and limestone ₹7,085 crore.
This is not only an import-substitution argument. A deeper domestic chain can create more value through Indian exploration, extraction, processing and manufacturing. India already ranks fourth globally in iron ore, second in limestone, third in zinc and fifth in bauxite. Odisha’s experience in operationalising mineral blocks gives the State a natural role in this larger national opportunity.
Long-life mines need long-term clarity
The mining sector presently works through around 14 categories of taxes, charges, fees and statutory payments. The Mines and Minerals (Development and Regulation) Amendment Act, 2026 was passed by Parliament on 13 August 2026 and received Presidential assent on 17 August 2026. It has come into force on 22nd August, 2026.
The law defines mineral-bearing land and inserts Section 9D into the MMDR Act 1957. State levies on mineral rights and mineral-bearing lands will follow conditions prescribed by the Central Government. The value of a common reference point is practical: States can plan revenues, operators can plan production and lenders can assess projects against a clearer horizon.
The next forty-five are Odisha’s forward story
Nationally, more than 720 mineral blocks have been auctioned and 105 are operational. Coal has 141 auctioned mines and 23 operating. Around 300 bidders have participated and 337 companies hold mining leases. Around 1,200 working mines generated approximately ₹2.32 lakh crore in royalty, while roughly 100 operational auctioned mines generated around ₹96,000 crore in premium.
The 2024 Supreme Court decisions created a pathway for transactions from 1 April 2005, with payments spread over twelve years from 1 April 2026 and interest relief for the earlier period. The amended law treats amounts already deposited with or recovered by a State as settled and provides the framework for future levies.
For Odisha, the most important number now may be 45. The first 34 operational blocks demonstrate what disciplined execution can unlock. The next 45 can deepen production, State revenue, jobs, district resources and India’s domestic mineral strength. That is how Odisha can carry its auction leadership into a new phase of operational leadership aligned with Atmanirbhar Bharat and Viksit Bharat 2047.